
The most critical car insurance renewal mistakes in the UAE include:
- Letting your car insurance policy lapse
- Entering an incorrect purchase start date
- Losing your No Claims Discount (NCD)
- Using High Or Low Market Valuations (IDV).
Why a Single Insurance Error Can Cost You Thousands in the UAE
A single insurance mistake, no matter how it’s made, neglect, haste or any insurance error you make can lead you to face legal consequences, fines, penalties and out-of-pocket expenses.
In case you forgot to renew your car insurance policy and there is a policy lapse, you won’t be covered in case of an accident.
Similarly, your premium price will increase if you forgot to claim your No-Claim Discount from your insurer.
You will get fines if you are caught driving without any car insurance, fines and vehicle impoundment can happen as per rules from RTA or TAMM.
How To Renew Your Car Insurance In UAE
So, a single mistake on your car insurance can lead you to face heavy financial losses.
| Policy Error | Administrative & Legal Impact | Financial & Claim Impact |
| Wrong Inception Date | Registration system mismatch | Uninsured gap; 100% claim rejection during gap |
| Expired Insurance (Grace Period) | AED 500 fine, 4 black points, vehicle impoundment | Legal liability for all third-party and personal damages |
| Under-Declaring IDV | None | Financial shortfall during total loss write-offs |
| Material Non-Disclosure | Policy cancellation | Policy declared void; complete claim denial |
| Unapproved Workshop Repairs | Loss of warranty | Out-of-pocket payment; non-reimbursement |
Here you go with,
Top 10 Car Insurance Mistakes in UAE & How To Avoid Them
Here are the top 10 car insurance mistakes that are costly for you. Before you confirm your car insurance renewal, review this complete 10-point car insurance renewal checklist or simply know these top 10 motor insurance mistakes you must avoid to ensure your coverage remains 100% valid.
Mistake 1: Policy Date & Renewal Timing Mistakes Before You Pay
Entering an incorrect policy start date is one of the most common mistakes drivers make during quick online checkouts.
Wrong Purchase Date on Car Insurance & Inception Date Gaps
If your current policy expires on October 15th at 11:59 PM, but you set your new policy inception date to start on October 18th, you create a 3-day uninsured coverage gap.
If an accident occurs during this window, your claim will be rejected.
Always verify your current Mulkiya expiration date and match your new policy inception date down to the exact day.
Mistake 2. Confusing the RTA 13th-Month Grace Period with Insurance Coverage
The most common and most costly car insurance mistake is the confusion of the 13th-month insurance coverage(granted by licensing authorities: Dubai RTA or Abu Dhabi TAMM).
People think they are insured even in the 13th month, but they are not; it is a grace period given to allow time to get a vehicle inspection and renew Mulkiya.
Your car insurance actually expires on day 365. The grace period(the 13th month) is given so you can renew your insurance and your car Mulkiya.
During this time, if there is an accident and you have not bought new insurance or did not renew your insurance, you won’t be covered you have to bear many of the expenses.
Mistake 3. Letting Your Policy Lapse (Without Car Insurance Fine)
You must not have any gap in your vehicle’s insurance policy; continuous cover confirms policy reinstatement.
If your motor policy lapses, it leaves you exposed to immediate legal and financial penalties under UAE traffic law.
Driving an uninsured vehicle triggers an AED 500 fine, 4 black points on your driving license, and potential vehicle impoundment for 7 days.
Also, if you create a coverage gap in the insurance, the insurer may consider your vehicle as higher risk, and your premiums may get higher.
Set your renewal reminders at least 2 to 3 weeks before your policy’s official expiration date.
Mistake 4: Failing to Transfer Your No Claims Discount (NCD)
If you have driven for 1 to 5 years without filing an at-fault claim, you are legally entitled to a No Claims Discount (NCD) that can reduce your renewal premium by up to 30%–50%.
When switching to a new insurance provider, drivers frequently forget to request or upload their official NCD certificate from their previous insurer. As a result, the system charges them the baseline full rate.
How No Claim Discount Works In the UAE?
How To Get an NCB Document From Insurance?
To get an NCB Document, contact your insurance company with your Emirates ID, Insurance policy number, and vehicle details around a month before your policy expires.
Always request an official NCD letter from your outgoing insurer before renewing to ensure your earned discount is applied.
Mistake 5. Miscalculating the Insured Declared Value (IDV) of Your Vehicle
Setting a high value for your car(the Insured Declared Value) increases your annual premium only. There is a myth that if your car has to consider a write-off in case of a total loss accident or a vehicle theft, you will get that high value for your car; no, you will only get the actual market value of the vehicle at the time of the crash.
Hence, over insuring or under isnuring(The Insured Declared Value), IDV is a costly motor insurance mistake that people in the UAE often make.
Mistake 6. Accepting Auto-Renewal Quotes Without Market Comparison
Renewing motor insurance automatically without first evaluating market rates means missing out on promotional rates, free roadside assistance add-ons, or lower deductibles offered by rival providers.
Many policyholders pay what is known in the industry as a “loyalty tax.” Insurers often issue automatic renewal notices with higher rates or basic default terms, assuming existing customers won’t shop around.
Comparing quotes across top UAE insurers ensures you secure the best cover at the most competitive price point.
How To Get The Cheapest Car Insurance In the UAE?
Mistake 7. Dropping Essential Policy Add-Ons to Save Money
You want to spend less on insurance and buy the lowest possible upfront, and just skip the policy add-ons that are costly mistakes in future.
- Agency Repair vs. Garage Repair: Standard comprehensive policies for cars older than 3 to 5 years default to garage/workshop repair. If you want repairs done strictly at the official dealer dealership using OEM parts, you must explicitly opt for Agency Repair.
- Natural Calamity & Flood Cover: Crucial for UAE storm and rain events. Basic third-party liability policies do not cover flood damage to your own vehicle.
- Off-Road Cover: Mandatory for SUV and 4×4 owners who drive on unpaved roads, desert tracks, or dunes. Standard policies strictly void claims originating off-road unless this extension is active.
Looking for agency repairs at the best market price?
Comprehensive Vs. Third-party Car Insurance: What You Must Choose?
Mistake 8. Typos & Material Non-Disclosure on Proposal Forms
Insurers rely on the exact details submitted in your proposal form to calculate risk and issue valid policies. Think about any error, like typing in a single wrong character from your VIN.
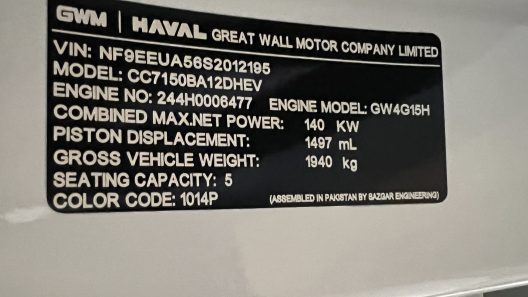
- Clerical Errors: A single wrong digit in your 17-character Chassis Number (VIN), Engine Number, or Emirates ID will cause automated RTA/TAMM registration matching system failures, blocking your Mulkiya renewal.
- Material Non-Disclosure: Failing to declare performance modifications (engine tuning, exhaust upgrades, structural modifications) or commercial vehicle usage gives the insurer legal grounds under CBUAE regulations to declare the policy void ab initio (void from the start) and reject all subsequent claims.
Mistake 9. Delaying Police Notification & Moving Vehicles Without a Report
In the UAE, an official Traffic Police Report is mandatory for any motor insurance claim to be accepted or processed.
- Green Police Report: Issued to the party not at fault; damage is covered 100% by the at-fault party’s insurer with zero excess deductible.
- Red Police Report: Issued to the driver at fault; subject to your policy’s excess deductible.
Moving your vehicle without documenting the scene or delaying calling Dubai Police, Abu Dhabi Police, or Saeed immediately after an incident can lead to unverified accident circumstances and total claim denial.
How To File A Car Insurance Claim In The UAE?
Mistake 10. Authorizing Garage Repairs Before Loss Surveyor Inspection
Taking your damaged car directly to a private workshop and starting repair work before an official loss assessor or insurance surveyor inspects the vehicle will result in an immediate claim rejection.
Insurers must inspect the damage, estimate repair costs, and assign the job to an authorized facility.
Always submit your police report and wait for formal repair authorization before handing over your keys.
Ready to renew your car insurance without the guesswork?
Avoid policy gaps, protect your No Claims Discount, and compare top-rated UAE motor insurers side-by-side in under 2 minutes.
FAQ
If you want to save money, it’s a good idea to check out different insurance options to see if you can find better deals. Look for companies such as BuyAnyInsurance, with good customer service and strong financial ratings, to ensure you’re getting quality coverage.
Assess your needs and budget. Research reputable insurance companies. Compare quotes from multiple providers. Look for coverage tailored to new drivers. Consider factors like premiums, deductibles, and coverage limits. Check customer reviews and ratings for customer service. Ask about discounts for new drivers or completing driver safety courses.
If you provided incorrect information to your insurance provider, contact them immediately to rectify the mistake. Provide the correct details and ask for your policy to be updated accordingly. Be prepared for potential adjustments to your premiums or coverage. It’s crucial to address inaccuracies promptly to ensure you have the appropriate coverage.
The decision between third-party liability (TPL) insurance and comprehensive insurance hinges on your requirements:
TPL insurance covers damages to others but not your vehicle.
Comprehensive insurance covers damages to both others and your vehicle.
Select the option that aligns with your coverage preferences and financial considerations.
Steering wheel locks, car alarms, GPS trackers, immobilizers, wheel locks, and kill switches are among the best options. Using a combination of these devices can boost security and deter theft effectively.
Read also:
How to Lower Your Car Insurance Costs in Dubai
Temporary Car Replacement in Car insurance
[…] Avoid These Top 10 Mistakes When Purchasing Car Insurance […]