

Third-party car insurance, also called third-party liability insurance (TPL), is the minimum motor insurance cover required for vehicles in the UAE under the CBUAE Rulebook on Motor Insurance Enforcement.
It covers your legal liability for covered injury, death, or property damage you cause to other parties in an accident; it does not cover your own vehicle damage.
How Much Does Third-Party Car Insurance Cost in the UAE in 2026?
In 2026, third-party car insurance in the UAE is approximately AED 610–1,200 annually. Your actual premium can be higher or lower depending on your car, driver profile, claims history, and the coverage offered by the insurer.
Want to understand what affects your car insurance premium? See our guide on how to lower your car insurance costs in Dubai.
The tool below will help you estimate the cost of third-party insurance as per your vehicle’s engine and type.
UAE Third-Party Motor Insurance Premium Estimator
Calculate your estimated premium range based on the official Central Bank of the UAE (CBUAE) regulatory tariff guidelines.
How Your Third-Party Premium is Actually Calculated
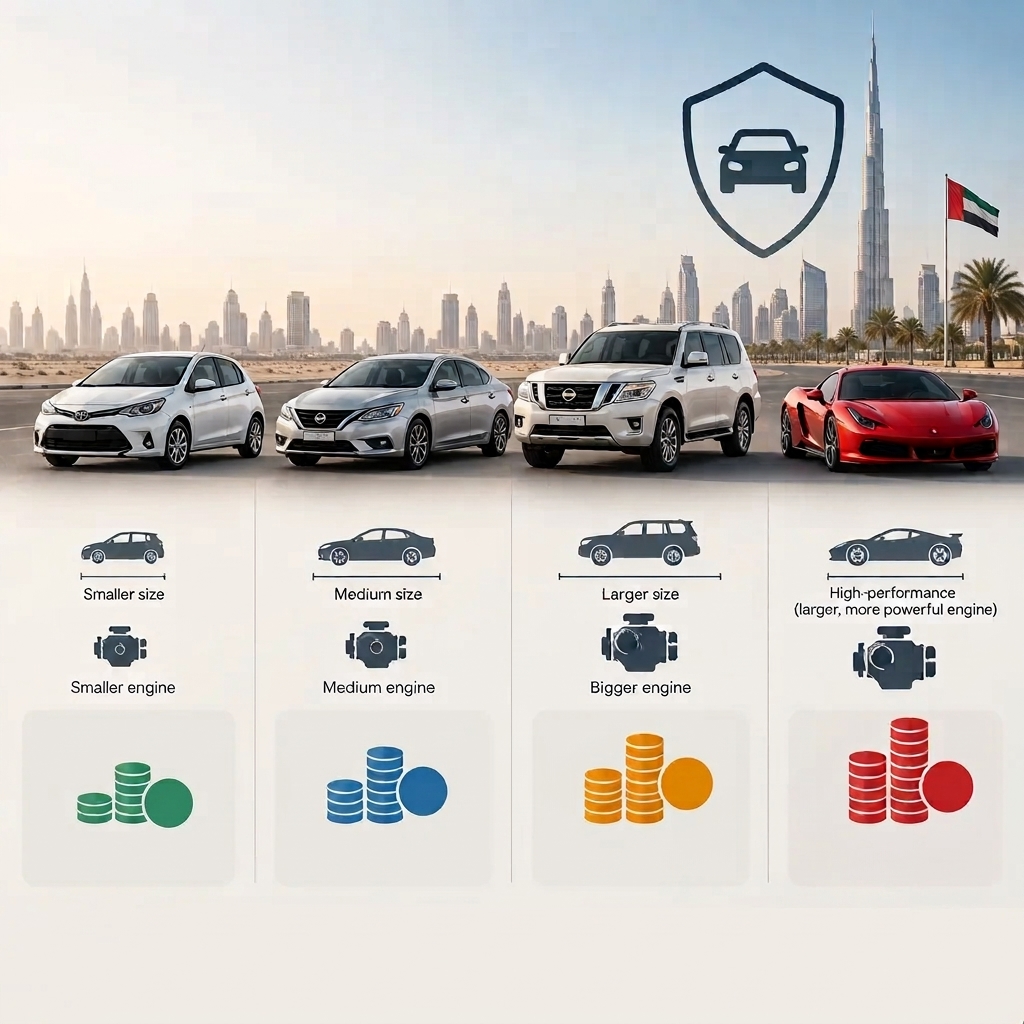
The value of your car does not change your Third-Party Liability (TPL) price.
If you drive a 15-year-old car worth AED 5,000 or a brand-new luxury car worth AED 500,000, your third-party insurance price will be almost identical if the engine sizes are the same.
This is because TPL insurance only pays for the other person’s damages; it never fixes your own car.
The Central Bank of the UAE sets the prices based on just three simple factors [SR1]:
- Engine Size & Cylinders: The government sets fixed legal minimum and maximum price limits based entirely on your car type (Sedan vs. SUV) and engine (4, 6, or 8+ cylinders).
- No-Claims Bonus (NCB): If you have a clean driving history with zero accidents over the past year, insurance companies can give you up to a 20% discount. (No-Claim Bonus Facts)
- Driver’s Age: If you are under 25, insurers view you as a higher risk. They will charge you a higher premium or set a higher out-of-pocket fee if you cause an accident.
Is Third-Party Insurance Compulsory in the UAE?
Yes. Under UAE federal traffic regulations, Third-Party Liability (TPL) motor insurance is legally mandatory for every single motorized vehicle operating on public roads.
If you want to register your car through RTA, EVG, or MOI, or apply for your Mulkiya renewal, you cannot do it without having at least third-party insurance.
Every driver in the UAE knows that failure to maintain this active coverage results in immediate fines, black points on your traffic profile, and the impounding of your vehicle.
What Does Third-Party Liability Cover?
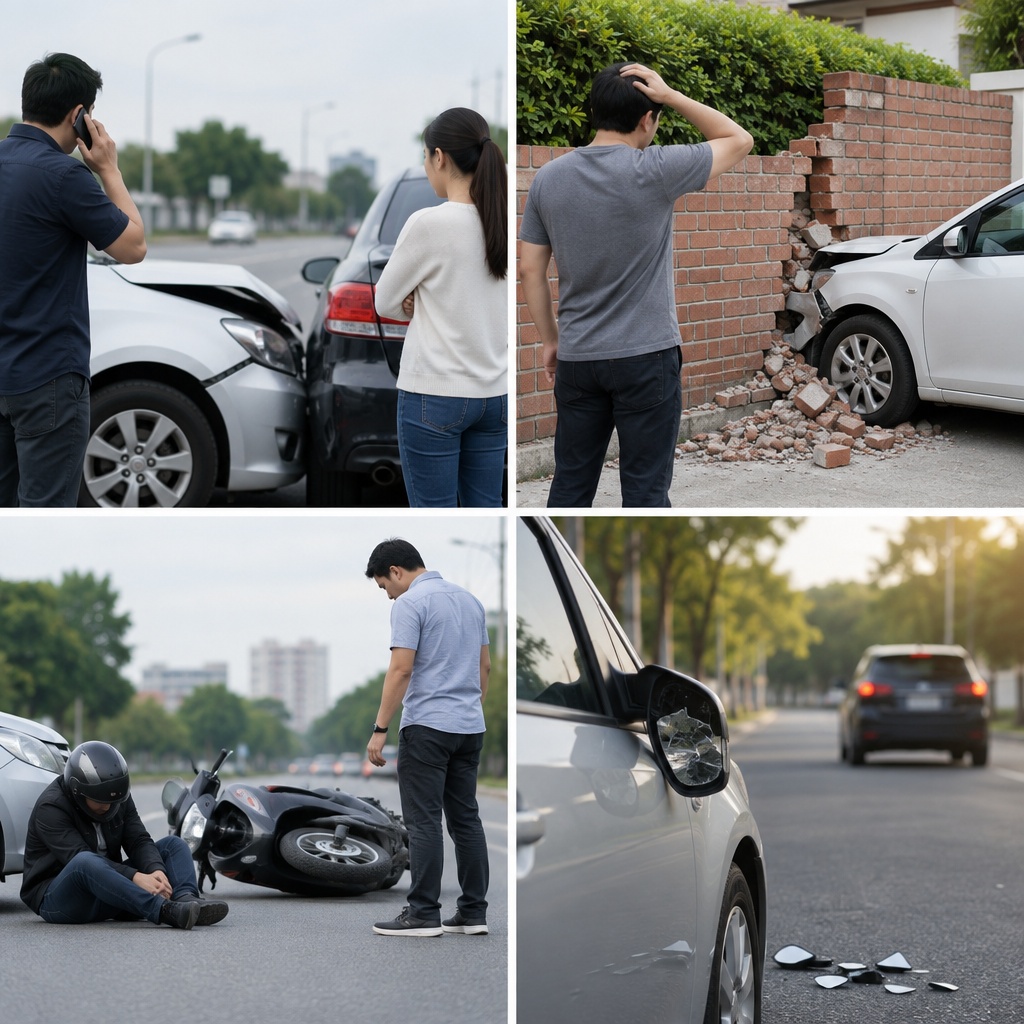
In the event of an accident involving the insured vehicle, the following outcomes are eligible for claims:
- Property Damage: Repairs to other people’s cars, buildings, fences, or public infrastructure (legally capped at a minimum of AED 2,000,000 per accident).
- Third-Party Bodily Injury & Death: Medical bills, ambulance costs, rehabilitation, and court-awarded blood money (Diyya) for affected third parties (Unlimited cover by law).
- Litigation Expenses: Legal fees resulting from a lawsuit brought against you by an affected third party.
If the accident is your fault:
Your insurance provider will pay compensation to the other party.
If the accident is not your fault:
The other person’s insurance provider will pay compensation directly to you.
Personal Injury Compensation: Who Gets Paid
The table below shows who receives medical and injury compensation in an at-fault accident, highlighting the difference between a standard Third Party policy and one with the Personal Accident Endorsement.
| Person Injured in the Accident | Standard TPL Policy (Basic Law) | TPL + Personal Accident Endorsement |
|---|---|---|
| People in the OTHER vehicle (Drivers and their passengers) | PAID They are 100% legal third parties. | PAID Covered under the standard TPL portion. |
| Pedestrians / Cyclists | PAID They are 100% legal third parties. | PAID Covered under the standard TPL portion. |
| Your Friends / Colleagues / Strangers (Passengers inside your car) | PAID The law views unrelated passengers as third parties. | PAID Covered (often with higher/simpler payout limits via the rider). |
| Your Immediate Family (Spouse, Parents, and Children inside your car) | ❌ NOT PAYABLE Explicitly excluded by UAE law from basic TPL. | PAID The rider explicitly adds them back into the policy coverage. |
| Your Employed Staff (Your private driver, maid, or nanny inside your car) | ❌ NOT PAYABLE Excluded by TPL law; usually falls under labor/visa insurance. | PAID The rider extends protection to employees in the vehicle. |
| YOU (The Driver / Policyholder) | ❌ NOT PAYABLE You cannot be a “third party” to your own liability. | PAID Provides you with a fixed lump sum for injury, disability, or death. |
What is a personal accident endorsement in third-party insurance?
Personal accident insurance is a rider that is usually bought with a third-party insurance.
Since third-party insurance does not cover injuries to you or your family if you are at fault in an accident, buying a personal accident endorsement pays medical bills for your immediate family.
Why Buy Third-Party Insurance?
You buy third-party insurance to legally drive a car in the UAE while spending the minimum on insurance. Third-party insurance protects you from costly repairs to the other party if you cause the accident.
Third-party insurance is good for:
- A car that is not worth much money;
- When a policyholder can’t afford higher cover;
- When the requirement is a minimum cover.
Third-party insurance is not suited for:
- Expensive cars;
- Living in high-crime areas;
- Living in climates prone to natural disasters.
How To File A Claim Under Third-Party Insurance?
- Inform the police ASAP and get a police report.
- Do not argue with involved persons under any circumstances.
- Inform the insurance provider as soon as possible, whether or not you plan to file a claim.
- Follow all the instructions given by the insurance company.
- Provide the police report, driver’s license, and vehicle registration to the insurance provider.
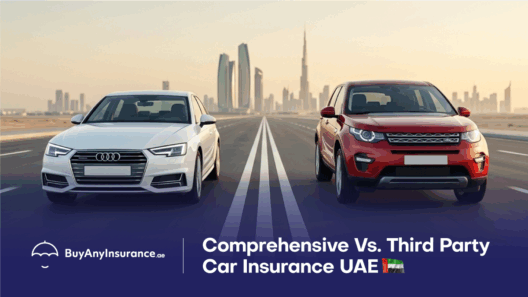
Third-Party Liability (TPL) vs. Comprehensive Insurance
The single greatest source of confusion for UAE motorists is assuming that “having insurance” means “being fully protected.”
Third-party liability, or third-party insurance, protects others from your mistakes; it does not protect you.
| Feature / Scenario | Third-Party Liability (TPL) | Comprehensive Insurance |
|---|---|---|
| Legal Compliance | Complies fully with UAE minimum laws | Complies fully with UAE minimum laws |
| Damage to the Other Car | Covered | Covered |
| Injuries to Other Drivers/Pedestrians | Covered | Covered |
| Damage to Your Own Car (At-Fault) | 🔴 Not Covered | Covered |
| Theft or Total Fire Loss | 🔴 Not Covered | Covered |
| Natural Disasters (Floods/Storms) | 🔴 Not Covered | Covered (Usually optional or standard add-on) |
| Premium Cost | Low (Fixed baseline rates) | Higher (Calculated on vehicle value) |
If you’re deciding between the two, see our detailed guide to third-party vs. comprehensive car insurance.
Real-World UAE Scenarios For Third-Party Insurance
Scenario A: The Floods & Rain Damage
If your vehicle suffers engine hydrostatic lock or body damage due to flash flooding or accumulated rain, a standard TPL policy will not pay.
For natural disaster protection, you need a comprehensive policy with explicit storm add-ons.
Scenario: Your old car is worth AED 15,000
Is TPL sensible?
It can be. If your car has a relatively low market value and you are comfortable paying for repairs after an accident, third-party insurance can be a practical, lower-cost option.
Scenario: Your car is financed
Is TPL appropriate?
If your finance agreement requires comprehensive insurance, you cannot simply choose TPL to save money. Check the lender’s insurance requirement first.
Scenario: Parking Lot “Hit-and-Runs”
You park your vehicle outside a mall and find your bumper smashed with no note left by the perpetrator. If you carry TPL, you must pay for the entire repair out of pocket.
Scenario: Driving to Oman (The Orange Card Cross-Border Rule)
A standard UAE Third-party insurance is strictly territorial; its geographical limits end at the UAE border.
If you plan to drive to Muscat or Salalah, you must secure an Orange Card or buy short-term Omani third-party liability directly at the border crossing.
How To Find Cheap Quotes For The Best Third-Party Insurance?
Compare third-party car insurance quotes from leading UAE insurers in one place and choose the cover that fits your budget.
Read more…
How to Lower Your Car Insurance Costs in Dubai
Avoid These Top 10 Mistakes When Purchasing Car Insurance
Benefits of Buying Car Insurance Online
Contact Us:






[…] should think carefully and research before buying it, and also determine your needs. Do you want third party insurance or comprehensive insurance , what is your budget? Need basic coverage or extra features? All you […]
[…] Third-party liability cover […]
Thank you very much for sharing, I learned a lot from your article. Very cool. Thanks.
Thanks for sharing. I read many of your blog posts, cool, your blog is very good.
Thank you for your sharing. I am worried that I lack creative ideas. It is your article that makes me full of hope. Thank you. But, I have a question, can you help me?
Your point of view caught my eye and was very interesting. Thanks. I have a question for you.
Can you be more specific about the content of your article? After reading it, I still have some doubts. Hope you can help me.
Can you be more specific about the content of your article? After reading it, I still have some doubts. Hope you can help me.
Can you be more specific about the content of your article? After reading it, I still have some doubts. Hope you can help me. https://www.binance.com/ar/register?ref=PORL8W0Z
[…] or third-party car insurance“: Are you typing the exact same query into chat engines or Google? You are not the only one […]