
The car insurance cost is increasing in Dubai even for drivers with clean driving records and the reasons are:
- Rising car claims
- Cost of integrating AI and improving digital insurance systems
- The rising costs of maintaining regulatory compliance by Central Bank of the UAE
- Geopolitical conditions of the area
- New form of insurance including war insurance, marnie insurance, cyber-risk insurance.
These increases in insurance costs in Dubai and the GCC is published in Alpen Capital’s report published on May 20th, 2026.
Here’s what to know about car insurance prices in Dubai, why they can seem expensive and what you can do when a quote exceeds your budget.
Before renewing, review our car insurance renewal guide for the UAE for the steps to follow and the policy details to check.
How Much Does Car Insurance Cost in Dubai?
Car insurance in Dubai can cost anywhere from AED 500 to AED 4,000+ each year.
No single premium applies to every car owner.
Typically, an average car insurance cost in Dubai is:
| Type of car insurance | Indicative annual price |
|---|---|
| Third-party liability insurance | Around AED 500–1,200 |
| Comprehensive car insurance | Around AED 1,200–4,000+ |
Disclaimer: These are broad market estimates, not guaranteed prices or live quotations.
Luxury vehicles and specific driver profiles may get other quotes that do not fall in the given range.
For a closer look at typical prices and what affects them, read our guide to third-party car insurance costs in the UAE.
Now, it is time to read about the cost and coverage of a comprehensive car insurance.
How Comprehensive Car Insurance Saves You From Out-of-Pocket Expenses?
Why Are Insurance Premiums Different For Different Drivers & Cars?
Insurance prices fluctuate because they are directly linked to the type of coverage you choose, the vehicle you have and your driving profile.
Each car and each driver may have a different motor insurance premium because of different driving profiles and the vehicle condition.
So you can’t say that if your friend has got a car insurance costing AED 1200 annually, you will also get the same premium for your car insurance policy.
What Factors Affect Insurance Premium Price In Dubai?
The factors that affect the cost of insurance premium in Dubai are:
- Insurers(different companies quote different premium)
- Agency repair Vs Non-agency repairs
- Insurance deductibles
- Add-ons you select
- Annual premium
- Coverage (third party, comprehensive, temporary car insurance)
- Exclusions and limits
To get a relevant estimate of your car insurance, you have to use your own vehcicle and your own driver’s details to get a quote.
How about if you get a competitve car insurance from trusted insurers in Dubai.
Why is third-party insurance cheaper than comprehensive insurance?
Third-party liability insurance is cheaper because it just covers your legal liability for injury to other people and damage to their vehicle. It does not cover damage to your own car.
Comprehensive insurance includes third-party and also covers damage to your own vehicle.
Because comprehensive insurance can cover a wider range of losses, it generally costs more.
Still the price difference between the two types of car insurance coverage premiums varies according to the vehicle, driver profile and insurer.
If you’re deciding which type of cover suits your car and budget, read our guide to third-party versus comprehensive car insurance.
Why Is Comprehensive Car Insurance Pricier Than a Third-Party Policy?
What Makes Car Insurance Expensive in Dubai?
Several factors can influence your vehicle insurance premium in Dubai and make it expensive. Understanding them can help explain why a quote for your car may be higher than you expected.
1. Your car’s make, model and market value
A vehicle with a high market value may cost more to insure because a major repair or total loss could result in a larger claim. Expensive replacement parts, specialist repairs and limited availability of components can also affect the insurer’s potential costs.
For example, insuring a luxury SUV may cost more than insuring an economy sedan, even if both vehicles are driven for similar purposes.
2. Your driving experience and claims history
Insurers may consider your age, driving experience, licence history and previous claims when calculating a premium.
3. The type of coverage you choose
The coverage you select affects both the premium and the protection available under your policy.
Third-party liability insurance is generally less expensive because it does not cover damage to your own vehicle. Comprehensive insurance provides broader protection, but the price depends on the benefits included.
4. Agency repair versus non-agency repair
Agency repair generally means that eligible repairs are carried out through the vehicle manufacturer’s authorised repair network, so it increase the premium. Non-agency repair uses an insurer-approved workshop outside that network so you can see a lesser premium.
5. Your deductible or excess
The deductible, also called the excess, is the amount you may need to pay towards a covered claim, as specified in your policy.
Some policies offer different premiums depending on the deductible selected. A higher deductible may reduce the annual premium, but it can leave you paying more yourself if you need to make a claim.
To understand how the excess affects your out-of-pocket costs and insurance premium, see our guide to car insurance deductibles in the UAE.
6. Optional benefits and policy limits
Additional benefits can increase the cost of your insurance. Depending on the insurer and policy, these may include roadside assistance, a replacement car, Oman cover or off-road cover.
These benefits are not equally useful to every driver. Someone who regularly travels outside the UAE may value a different set of benefits from someone who mainly drives within Dubai.
Review what is included in the quoted premium, what costs extra and which exclusions or limits apply. You may be able to choose a policy that better matches your needs without paying for benefits you are unlikely to use.
For example, before paying extra for a replacement-car benefit, find out what temporary car replacement insurance covers in the UAE and whether you need it.
Why Do Two Insurers Quote Different Prices for the Same Car?
It is common to get two different quotes from two different insurers and the reason can be that both policies can differ themselves.
One quote might include agency repair, while another uses an approved non-agency garage. One may have a lower deductible or additional benefits that are not included in the other.
Receiving different prices for the same vehicle can be frustrating, particularly when you have supplied the same information to each insurer.
To explore the providers available in the market, see our guide to car insurance companies in Dubai.
Find the most competitive car insurers in Dubai
Insurers do not necessarily assess every application in exactly the same way. They may use different pricing criteria, underwriting rules and approaches to evaluating risk.
Before deciding that one insurer is more expensive, compare the quotes side by side.
A lower premium can be a good option when the coverage suits your needs. But if the cheaper policy has a higher deductible or fewer benefits, the saving may involve a trade-off.
Overpaying for your car insurance?
Compare live quotes from top UAE insurers in under 2 minutes and save on your premium today.
Why Has Your Car Insurance Renewal Price Increased In Dubai?
Dubai drivers have observed an increase in renewal premiums this year because Dubai has experienced severe weather conditions(floods and hail), due to which there was a sharp rise in insurance claims.
Higher costs of repairs and spare parts are also adding to the increase in premium price.
Your insurer now reassesses the policy at renewal, and the price can change for reasons beyond your individual driving record.
How Can You Tell If Your Car Insurance Quote Is Too Expensive?
There is no universal price that determines whether a car insurance quote is too expensive. A premium that is reasonable for one vehicle and driver may be high for another.
How To Lower Car Insurance Premium In Dubai?
If your renewal quote in Dubai is higher than last year’s premium, take these steps.
1. Compare the old and new policies. Check whether the coverage, deductible, repair arrangements or optional benefits have changed.
2. Ask your insurer to explain the increase. Request clarification about any changes to the premium or policy terms. Do not assume the increase has one particular cause without confirmation.
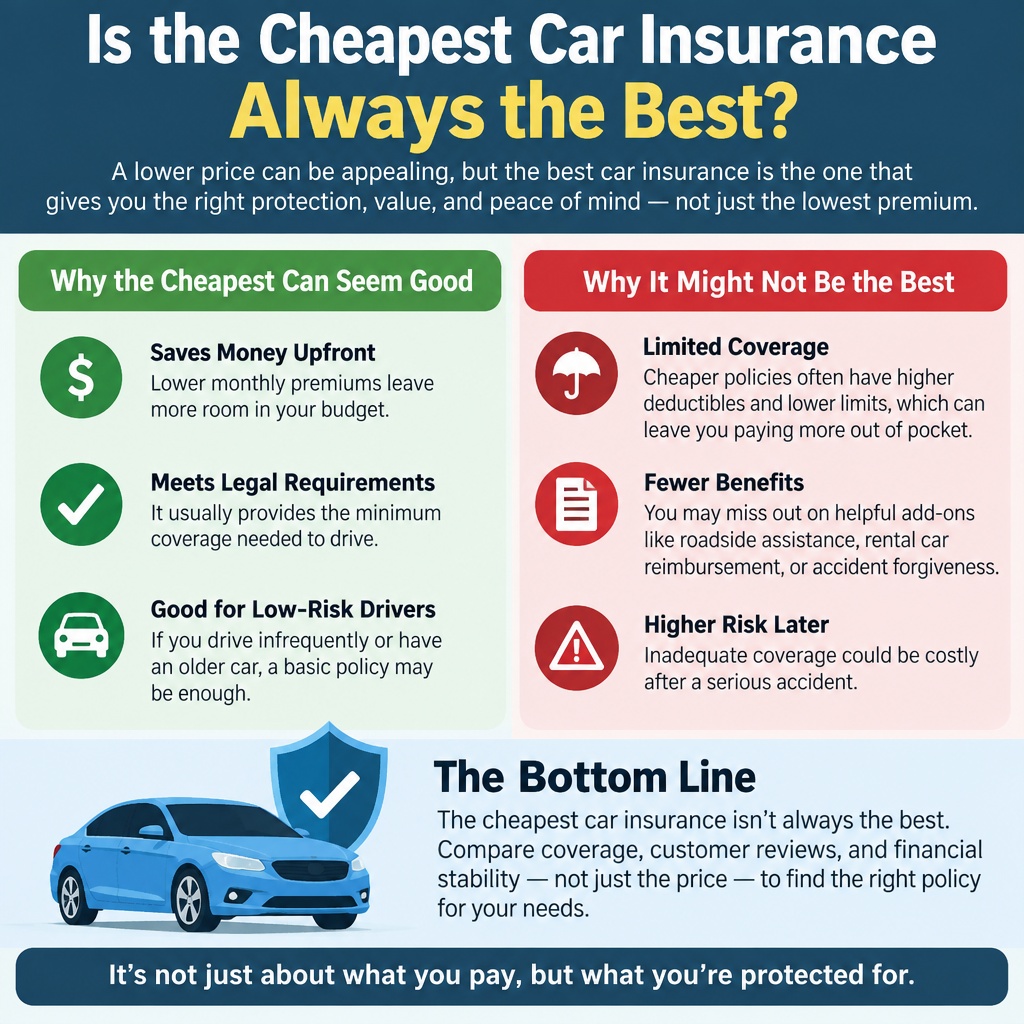
Before deciding on to buy the cheapest car insurance, read these tips to save your finances.
3. Request competing quotes. Use consistent vehicle and driver information so that you can make a more meaningful comparison.
4. Review your coverage requirements. Consider whether add-ons or optional benefits still suit your needs, but do not remove useful protection simply to reduce the price.
5. Compare the final cost and conditions. A lower renewal alternative is only a useful comparison when you understand the differences in coverage, excess and exclusions.
You do not have to accept the first price you receive. Comparing alternatives can help you understand whether another suitable policy is available at a more competitive premium.
How to Find More Affordable Car Insurance in Dubai
If your current quote is higher than expected, you have several options to explore without compromising protection you need.
For more practical ways to manage your premium, explore our guide on how to lower your car insurance costs in Dubai.
Compare Car Insurance Prices in Dubai
If you are unsure whether your current quote is competitive, comparing suitable policies is a practical next step.
Do not choose a policy on price alone. The aim is to find a premium that fits your budget while providing suitable protection for your car and circumstances.
FAQs
Yes, you can pay montlhy installments for your car insurance but there is a legal catch of how insurance works. UAE insurance needs to have valid 13 months insurance so the cars get registered.
If you want to pay monthly for car insurance you have to use a credit card with 0%interest EPP(Easy Payment Plan) or Buy Now Pay Later(BNPL) payment options in Dubai.
You better discuss the options with your insurer.
Not necessarily. The cheapest policy may have a higher deductible, fewer benefits or different repair arrangements. Compare the coverage and conditions against your needs before deciding.
You can request comparable quotes from multiple insurers, see if you can qualify for discounts, review the add-ons and consider insurance deductible carefully to reduce car insurance premiums in Dubai annually.
Yes. A claim-free record does not guarantee that your premium will remain unchanged. Renewal pricing may reflect changes in underwriting criteria, vehicle-related costs, policy terms or other factors. Ask your insurer to clarify the reason for your particular increase.
[…] Extensive Guide to Compare Car Insurance Prices in Dubai […]
[…] An Extensive Guide to Compare Car Insurance Prices in Dubai […]
[…] An Extensive Guide to Compare Car Insurance Prices in Dubai […]
[…] An Extensive Guide to Compare Car Insurance Prices in Dubai […]