
A car insurance claim in the UAE can be:
delayed, disputed, or rejected
because of:
- Failing to follow the policy conditions
- Provide inaccurate information
- Make a claim for damage that isn’t covered
- Failed to follow the claims procedure
In some circumstances, an insurer may also have the right to recover compensation it has already paid.
Not every mistake automatically invalidates a car insurance claim. The result depends on the type of insurance, the facts of the accident, the relevant policy terms and the applicable UAE motor-insurance rules.
If you have third-party or comprehensive car insurance, you must know what conditions can affect your claim so you can avoid unnecessary disputes and delays.
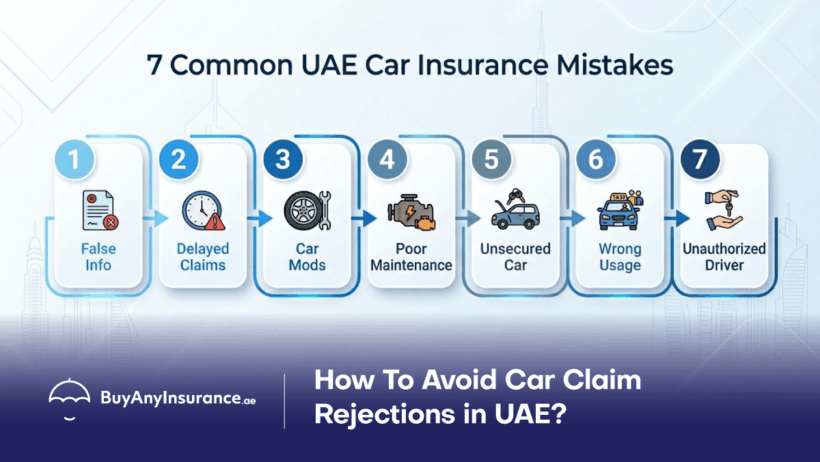
Here are seven mistakes to avoid, what they could mean for your claim, and how to protect yourself.
1. Providing False or Inaccurate Information
Providing false information, like important facts about your car, or providing fake documents and submitting a wrong report of how an accident happened is the first mistake that can reject your claim.
For example, problems may arise if you:
- Provide false information about the accident or who was driving.
- Conceal relevant information about the vehicle or its use.
- Submit altered receipts, repair estimates or other supporting documents.
- Exaggerate the damage or include unrelated damage in your claim.
What could happen?
If you provided inaccurate or false reports or tried to commit deliberate fraud or material misrepresentation, your insurance claim might get rejected.
You even have to face some legal consequences under applicable UAE law of providing false documents or attempting fraud.
How to avoid it: Provide truthful information, check your claim documents before submitting them, and correct any errors as soon as you discover them. Keep copies of the original accident report, photographs, original repair estimates and communications with your insurer.
Don’t allow any garage, even an insurance approved garage, to start tearing down your car for repairs unless the insurance has settled the claim.
2. Failing to Report the Accident or Follow the Claims Procedure
After an accident, always follow the right process to report the accident and notify the insurer as per policy requirements.
In the UAE, if you do not report an accident or delay notification to the insurer without a valid reason, the claim assessment can be complicated.
For example, if you arrange repairs before the insurer can inspect the vehicle, it may become harder to establish the extent and cause of the damage.
What could happen?
The insurer may request additional evidence, delay its decision, or raise concerns about whether the damage can be verified.
The consequences of late reporting or failure to follow a procedure depend on the circumstances, policy terms and applicable rules.
How to avoid it:
- Report the accident through the appropriate authorized process.
- Notify your insurer promptly and follow its instructions.
- Keep the accident report and claim reference number.
- Photograph the damage before repairs, where safe and practical.
- Obtain repair authorization when required by your policy or insurer.
Do not assume that a minor accident can always be handled privately without affecting a future claim.
3. Failing to Disclose Relevant Car Modifications
Modifications can change a vehicle’s specifications, value, performance or risk profile. You need to inform your insurer if you want to modify your car especially the modifications that affect the performance of the vehicle, engine changes and certain structural alterations.
You do not need to inform about ordinary accessories and modifications that do not directly impact the performance of the vehicle.
What could happen?
If a modification was not disclosed, the insurer may investigate whether it affects the policy or the loss being claimed.
So, it all depends on the policy wording, the nature of the modification and the applicable insurance policy rules.
Each modification you make on car does not cancel or reject an insurance claim; it is the policy and the modifications you made that cause the rejection.
How to avoid it: Contact your insurer before making a material modification. Ask if you declare it or if the modification is covered.
Do ask if the modification will change the premium or policy terms and keep a written record from your insurance agent for future reference.
4. Neglecting Vehicle Maintenance or Driving an Unsafe Car
Regular maintenance helps keep your vehicle roadworthy and can reduce the risk of breakdowns and accidents.
Problems can arise when you drive an unsafe vehicle or when a claim involves damage linked to a known mechanical defect.
Routine wear and tear and mechanical breakdown are different matters. Comprehensive car insurance does not cover every mechanical problem, the exact protection depends on your policy. Learn more about the differences between comprehensive and third-party car insurance.
What could happen?
Your insurance company has the right to ensure if the damage resulted from an accident or was a mechanical failure that happened due to a pre-existing technical problem.
How to avoid it: Keep your vehicle fit for driving on UAE roads both physically and technically.
If you do not fix or repair a damaged part and you had an accident because for instance, a broken bumper fell off and crashed into another car resulting in an accident, chances are your third party insurance claim may even be rejected.
5. Leaving Your Car Unlocked or Failing to Take Reasonable Precautions
Some drivers do not lock their cars and their vehcile is at increased risk of theft. You must take extra care if the vehicle is locked, especially if there are valuable things inside the car.
But not every theft that happened due to an unlocked vehicle can result in claim rejection. Some policies include the theft even if the car was left unlocked.
What could happen?
The insurer may investigate how the theft occurred and whether the circumstances fall within the policy’s cover.
How to avoid it:
- Lock your vehicle and close the windows when leaving it unattended.
- Keep the keys secure and avoid leaving them inside the vehicle.
- Follow any security requirements stated in your policy.
- Report theft promptly through the appropriate police process and notify your insurer.
Check the theft conditions in your policy rather than assuming that every lapse in security automatically invalidates a claim.
6. Using Your Car for a Purpose Not Covered by Your Policy
Your policy may specify the permitted use of your vehicle. For example, a car insured for private use may have different terms from a vehicle used for commercial deliveries or other business activities.
If you use the vehicle for other purposes not declared in the insurance, and it has led to an accident, may be your insurance claim gets rejected.
What could happen?
The insurer may assess whether the vehicle’s use falls within the agreed coverage and whether an exclusion applies. It all depends on the policy and the circumstances of the accident.
How to avoid it: Explain how you use your vehicle when obtaining insurance. If your circumstances change, for example, you begin using your car for work or deliveries, it is better to ask the insurer if your existing policy is fine for your current change.
If you intend to drive off-road, participate in motorsport or undertake another activity that may be excluded, check the policy before doing so.
7. Allowing Someone to Drive Without Checking Your Policy Conditions
Always check your insurance policy coverage before you lend your car to another driver.
If the insurance policy was for a driver more than 25 years of age but at the time of accident, somone else less than 25 years was driving the car, chances are your insurance claim gets rejected.
What could happen?
If the driver does not meet the policy conditions, the insurer may dispute or reject a claim or exercise other rights permitted by the policy and applicable rules.
How to avoid it: Check who is permitted to drive your insured vehicle before lending it to someone. Confirm any age, licence, or driver restrictions with your insurer, especially if the person will use the car regularly.
Never allow someone who is not legally permitted to drive the vehicle to do so.
What Should You Do If Your Car Insurance Claim Is Rejected in the UAE?
If your insurer rejects your claim, do not assume that the decision is final or that you have no options. Start by understanding the reason for the decision.
- Request the rejection reason in writing. Ask the insurer to explain the decision and identify the relevant policy provisions and supporting documents.
- Review your policy. Check the exclusions, claims conditions and coverage that apply to your situation.
- Provide missing evidence if appropriate. You can provide accident report, photographs, repair estimates or other requested documents.
- Ask the insurer to reconsider the decision. Explain why you believe the claim should be covered and provide relevant supporting evidence.
- Check the formal complaint process. If the dispute remains unresolved, consult the applicable UAE insurance complaint and dispute-resolution procedures, mostly it is Sanadak(official UAE platform to complain insurance).
UAE motor insurance rules tell how you can handle claim handling and what reasons and supporting documents you can provide when a claim is rejected. You can consult the CBUAE Rulebook for the applicable legal rules in the UAE.
When a claim for your car insurance gets rejected, it is not just one straight path that everyone has to follow; it varies from situation to situation.
Can I Cancel a Car Insurance Claim After Filing It?
Yes, you can cancel a car insurance claim even after filing it, but you must ask your insurer if he has already approved and issued a settlement.
For example, you may decide not to proceed with a claim if the repair cost is low or you want to explore another option.
Keep these points in mind:
- Contact the insurer in writing to explain that you want to withdraw the claim.
- Ask whether the withdrawal can still be processed at the current stage.
- Request written confirmation of the outcome.
- Do not assume that withdrawing the claim erases the accident from the insurer’s records or guarantees that your future premium will remain unchanged.
Withdrawing a claim is not the same as cancelling your car insurance policy. Policy cancellation has separate conditions and may have different financial consequences.
How to Protect Your Car Insurance Claim: A Quick Checklist
Before and after an accident, these simple steps can help you avoid common claim problems.
- Provide accurate information when buying or renewing your insurance.
- Report accidents through the appropriate authorized process.
- Notify your insurer promptly and follow its claims procedure.
- Keep photographs, accident reports, repair estimates and correspondence.
- Obtain repair authorization when required.
- Declare relevant modifications and changes in vehicle use.
- Check whether your policy permits the person driving your car.
- Read the exclusions and conditions before assuming a particular loss is covered.
Remember that a claim’s outcome depends on the facts, your policy and the applicable rules. If you are unsure about a condition, ask your insurer for clarification in writing.
Compare Car Insurance Options Before You Renew
The cheapest policy is not necessarily the best fit for your needs. When comparing car insurance in the UAE, look beyond the premium and check the coverage limits, exclusions, excess or deductible, repair conditions and claims procedures.
Review the available options and policy conditions before choosing cover for your vehicle.
FAQs
Yes. An insurer can reject a claim if the loss is not covered or if a you policy excludes the claim.
The rejection depends on the facts, policy wording and applicable UAE rules. You can request the reason for rejection and the supporting documents.
Ask for the rejection reason in writing then review your policy and if required provide any missing evidence that may help clarify the circumstances.
Can my car insurance claim be rejected if someone else was driving?
It depends on the policy conditions and the circumstances. Check the permitted-driver conditions, any age or licence restrictions, and relevant exclusions. A driver not individually named on a policy is not automatically excluded under every policy.
Does comprehensive car insurance cover every type of damage?
No. Comprehensive insurance generally covers a broader range of risks than third-party liability insurance, but exclusions, limits and conditions still apply. Check the policy wording to understand whether a specific type of damage is covered.
Related Articles
- How to Buy a Car in Dubai and Documents Required to Buy a Car
- How to Lower Your Car Insurance Costs in Dubai
- Compare Car Insurance Prices in Dubai
Need help choosing cover? Compare your options and review the policy conditions before purchasing or renewing your car insurance.
How do I claim car insurance for an accident not my fault?
If you have to claim a car insurance that is not your fault, you can claim the other driver’s car insurance company via third party car insurance.
Will my insurance pay if it wasn’t my fault?
You have to pay for the losses for the other driver, passengers and anyone else.
What must you pay before the insurance company will pay a claim?
You would have to pay deductibles. This is the amount that before the insurance company will pay anything on claim.
Related Articles:
How to Buy a Car in Dubai and Documents Required to Buy a car
How to Lower Your Car Insurance Costs in Dubai
Extensive Guide to Compare Car Insurance Prices in Dubai
Contact Us: